Retirement investment calculators come in two flavors: quick online tools that spit out a number, and structured guides that walk you through the math and the decisions behind it. After comparing seven of the most popular options, The Retirement Dilemma stands out as the best overall pick because its 15 proprietary calculators cover dilemmas most free tools ignore entirely, like sequence-of-returns risk and healthcare timing. For readers who want a simpler entry point, Retirement Calculator: How Much Money Do I Need to Retire? delivers a fast, no-nonsense number, while Your Retirement Equation is the strongest choice if you’re starting late and need catch-up strategies. The main tradeoff in this category is depth versus speed — the more thorough calculators demand more of your time but expose assumptions that quick tools hide. Read on for the full breakdown of each option.
Prime for Young Adults — start your free trial
Fast free delivery, streaming and member deals for eligible 18–24 year olds.
Try it freeAs an affiliate, we earn on qualifying purchases.
Key Takeaways
- The Retirement Dilemma earned the top spot because it’s the only option addressing decision dilemmas (when to claim Social Security, when to retire) rather than just crunching a savings target.
- Three of the seven products are essentially single-number calculators; if you already know your target number, paying for those again wastes money.
- The Retirement Account Calculator is the only pick with complete IRA and Keogh lookup tables, making it uniquely useful for pre-tax account planning despite feeling dated.
- Late starters get the most value from Your Retirement Equation, which frames everything around a countdown rather than an open-ended savings horizon.
- The two FIRE-oriented picks overlap heavily — buyers should choose based on whether they want a step-by-step system (Calculate Your FIRE Amount) or a philosophy-first approach (How Much Is Enough).
| The Retirement Dilemma: The 8 Retirement Planning Dilemmas You Need to Understand and Overcome, 15 Proprietary Calculators Included |  | Best Overall | Format: Book (digital/print edition) | Core Feature: 15 proprietary retirement calculators | Structure: 8 retirement planning dilemmas | VIEW LATEST PRICE | See Our Full Breakdown |
| How Much Is Enough: Calculating Your Early Retirement Number (Freedom Years: The Smart Path to Early Retirement Book 2) |  | Best for Beginners | Format: Book (digital/print edition) | Series: Freedom Years: The Smart Path to Early Retirement, Book 2 | Focus: Calculating an early retirement savings target | VIEW LATEST PRICE | See Our Full Breakdown |
| Calculate Your FIRE Amount: The Step-by-Step Guide to Saving, Investing, and Achieving Early Retirement |  | Best FIRE Roadmap | Format: Book (digital/print edition) | Topic: FIRE movement: saving, investing, early retirement | Structure: Step-by-step guide | VIEW LATEST PRICE | See Our Full Breakdown |
| Retirement Investment Planning: Turn Your Savings Into Reliable Retirement Income Using Social Security, Dividend Stocks, Bonds, Annuities, and Smart Withdrawal Strategies |  | Best for Withdrawal Strategy | Format: Book (digital/print edition) | Focus: Retirement income and withdrawal strategy | Topics Covered: Social Security, dividend stocks, bonds, annuities, withdrawal sequencing | VIEW LATEST PRICE | See Our Full Breakdown |
| The Retirement Account Calculator: Complete Savings and Withdrawal Tables for IRA and Keogh Plans |  | Best Reference Tables (Legacy Pick) | Format: Printed book with reference tables | Coverage: IRA and Keogh plans | Table Types: Savings accumulation and withdrawal schedules | VIEW LATEST PRICE | See Our Full Breakdown |
| Retirement Calculator: How Much Money Do I Need to Retire? | 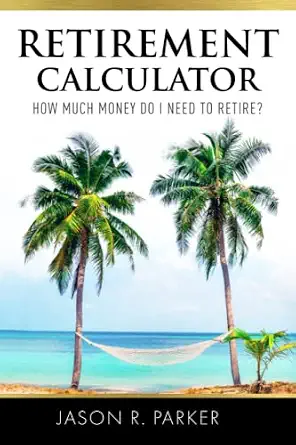 | Best Quick-Answer Pick | Format: Guide/calculator workbook | Primary Focus: Estimating total retirement savings needed | Approach: Input-based estimation | VIEW LATEST PRICE | See Our Full Breakdown |
| Your Retirement Equation: Calculate How Much You Need to Retire and How to Get It in Time |  | Best for Planning Beyond the Number | Format: Strategy and calculation guide | Primary Focus: Retirement number plus savings and timing plan | Approach: Calculation methods with practical advice | VIEW LATEST PRICE | See Our Full Breakdown |
| retirement investment calculator | Format | Approach | Target Stage | Experience Level |
|---|---|---|---|---|
| The Retirement Dilemma: The 8 | Book (digital/print edition) | Decision-oriented with quantitative tools | Pre-retirement and early retirement | Intermediate |
| How Much Is Enough: Calculatin | Book (digital/print edition) | Single-topic deep focus | Early accumulation phase | Beginner |
| Calculate Your FIRE Amount: Th | Book (digital/print edition) | Broad roadmap rather than single-topic focus | Full accumulation journey | Beginner to intermediate |
| Retirement Investment Planning | Book (digital/print edition) | Income-conversion strategies | At or near retirement | Intermediate |
| The Retirement Account Calcula | Printed book with reference tables | Static lookup reference | IRA/Keogh account holders | All levels, with caveats on data currency |
| Retirement Calculator: How Muc | Guide/calculator workbook | Input-based estimation | — | — |
| Your Retirement Equation: Calc | Strategy and calculation guide | Calculation methods with practical advice | — | — |
More Details on Our Top Picks
The Retirement Dilemma: The 8 Retirement Planning Dilemmas You Need to Understand and Overcome, 15 Proprietary Calculators Included
This pick makes the most sense for readers who want calculators embedded in a decision framework rather than raw math alone. Where Calculate Your FIRE Amount walks you through accumulation, this option focuses on the eight forks in the road — when to claim, how much to withdraw, whether to annuitize — and pairs each with a proprietary worksheet. Compared with Retirement Investment Planning, which covers income strategies more broadly, the calculator count here is the differentiator: fifteen tools for personalized analysis versus none. The tradeoff is density; the material leans technical, so a true beginner may need to read chapters twice. Readers already within a decade of retirement will get the most from it, while those still in accumulation mode may find the dilemmas premature.
Pros:- Fifteen proprietary calculators support personalized analysis rather than generic rules of thumb
- Organized around eight real retirement dilemmas, making the math purposeful
- Directly addresses decisions pre-retirees face, unlike accumulation-focused FIRE titles
- Strong companion for readers deciding between Social Security timing and withdrawal orders
Cons:- Technical depth may overwhelm readers without a basic finance vocabulary
- No customer ratings yet to validate how the calculators perform in practice
Best for: Pre-retirees within 10 years of leaving work who want structured tools for claiming and withdrawal decisions
Not ideal for: Absolute beginners who haven’t yet built savings — the dilemma framing assumes you have decisions to make
- Format:Book (digital/print edition)
- Core Feature:15 proprietary retirement calculators
- Structure:8 retirement planning dilemmas
- Target Stage:Pre-retirement and early retirement
- Approach:Decision-oriented with quantitative tools
- Experience Level:Intermediate
Our verdict“Buy this if you’re close to retirement and want the most calculator firepower in a single volume; skip it if you’re still in early savings mode.”
How Much Is Enough: Calculating Your Early Retirement Number (Freedom Years: The Smart Path to Early Retirement Book 2)
This option stands out for answering the single most paralyzing question in early retirement: what’s my number? Compared with Calculate Your FIRE Amount, which covers the full FIRE journey from saving to investing, this volume narrows to one calculation and explains it plainly — a better fit for someone who wants one clear answer rather than a full curriculum. As Book 2 of the Freedom Years series, it also benefits from a structured learning path, though that serial format is the tradeoff: readers wanting income strategies after quitting will need the next installment, whereas Retirement Investment Planning bundles withdrawal tactics in one place. It’s a low-commitment entry point, not a complete reference.
Pros:- Narrow, focused scope makes the core calculation easy to grasp quickly
- Plain-language approach suits readers new to FIRE concepts
- Part of a series, so readers can continue learning in sequence
- Translates abstract savings goals into a concrete personal number
Cons:- Requires purchasing additional series volumes for full coverage of investing and withdrawal
- Description lacks worked examples, so detail depth is hard to verify before buying
Best for: Early-career savers who feel stuck because they don’t know their target number and want a focused, plain-language answer
Not ideal for: Readers wanting an all-in-one retirement manual — this deliberately covers only the target-number calculation
- Format:Book (digital/print edition)
- Series:Freedom Years: The Smart Path to Early Retirement, Book 2
- Focus:Calculating an early retirement savings target
- Target Stage:Early accumulation phase
- Approach:Single-topic deep focus
- Experience Level:Beginner
Our verdict“Pick this if you want a short, focused answer to ‘how much do I need’ without wading through a full FIRE manual.”
Calculate Your FIRE Amount: The Step-by-Step Guide to Saving, Investing, and Achieving Early Retirement
Where How Much Is Enough solves one calculation, this guide delivers the end-to-end FIRE playbook — saving rates, investment strategy, and the target number in one volume. That breadth is its strength and its weakness: compared with The Retirement Dilemma, which goes deep on late-stage decisions with fifteen calculators, this book spreads itself across the whole journey, so advanced investors may find the material too familiar. For someone discovering FIRE for the first time, though, the step-by-step structure means fewer gaps — you won’t need three books to see the whole picture. The tradeoff is precision; the dilemmas and withdrawal-order questions that matter most at the finish line get less attention here than in the Retirement Dilemma pick.
Pros:- Covers the entire FIRE journey from savings rate to investment plan in one book
- Step-by-step structure suits readers who want an ordered roadmap
- Accessible to both beginners and intermediate savers
- Eliminates the need to buy multiple volumes for basic coverage
Cons:- Content may be too basic for advanced investors
- Lacks edition and publication details, making sourcing a current copy harder
Best for: Readers new to the FIRE movement who want saving, investing, and target calculations covered in one sequential guide
Not ideal for: Experienced investors who already understand index investing and safe withdrawal rates — too much will be review
- Format:Book (digital/print edition)
- Topic:FIRE movement: saving, investing, early retirement
- Structure:Step-by-step guide
- Target Stage:Full accumulation journey
- Approach:Broad roadmap rather than single-topic focus
- Experience Level:Beginner to intermediate
Our verdict“Choose this for your first FIRE book if you want the whole method in one pass; skip it if you’re past the basics.”
Retirement Investment Planning: Turn Your Savings Into Reliable Retirement Income Using Social Security, Dividend Stocks, Bonds, Annuities, and Smart Withdrawal Strategies
Every other title in this lineup focuses on getting to retirement; this one starts where they stop. Once you’ve computed a number with How Much Is Enough or Calculate Your FIRE Amount, you still face the question those books largely defer: how do you turn a portfolio into monthly income without running out? This option addresses Social Security timing, dividend stocks, bonds, annuities, and withdrawal sequencing — a wider income toolkit than The Retirement Dilemma offers, though without that book’s calculator worksheets. The tradeoff is that annuity and Social Security rules change, so a print edition ages faster than pure-math titles. It’s the missing second half of most retirement libraries.
Pros:- Focuses on the withdrawal phase, which most retirement calculators and books ignore
- Covers a wide income toolkit: Social Security, dividends, bonds, and annuities
- Smart withdrawal strategies directly address longevity risk
- Complements number-focused titles like How Much Is Enough
Cons:- Social Security and annuity rules change frequently, so content can date quickly
- No customer ratings available to gauge practical accuracy
Best for: Retirees and near-retirees who have saved enough and now need a concrete plan for drawing income from it
Not ideal for: Young savers still building their portfolio — withdrawal sequencing won’t be actionable for decades
- Format:Book (digital/print edition)
- Focus:Retirement income and withdrawal strategy
- Topics Covered:Social Security, dividend stocks, bonds, annuities, withdrawal sequencing
- Target Stage:At or near retirement
- Approach:Income-conversion strategies
- Experience Level:Intermediate
Our verdict“Buy this after you’ve hit your number — it’s the rare guide that covers what to do with the money once you stop working.”
The Retirement Account Calculator: Complete Savings and Withdrawal Tables for IRA and Keogh Plans
This is the odd one out — a printed table reference rather than a narrative guide, and that’s exactly its appeal for a specific reader. Instead of explaining philosophy like Calculate Your FIRE Amount, it lets you look up savings and withdrawal figures for IRA and Keogh plans directly, no math required. Compared with the fifteen calculators in The Retirement Dilemma, it’s rigid: tables assume fixed assumptions and can’t adapt to your personal situation the way a worksheet can. The bigger caveat is age — Keogh plans are a legacy vehicle, and contribution limits have shifted repeatedly since publication, so treat the numbers as illustrative. For quick lookups and historical context, though, nothing else in this lineup works the same way.
Pros:- Instant lookup format requires no calculation on the reader’s part
- Covers both accumulation and withdrawal tables in one reference
- One of the few resources addressing Keogh plans specifically
- Useful as a historical reference for how retirement planning assumptions evolved
Cons:- Legacy publication date means figures don’t reflect current contribution limits or tax rules
- Static tables can’t personalize for individual situations the way worksheet-based calculators can
Best for: Readers who prefer printed lookup tables for IRA planning, or those managing legacy Keogh accounts from self-employment
Not ideal for: Anyone wanting current figures — the tables predate modern contribution limits and can’t match interactive calculators for accuracy
- Format:Printed book with reference tables
- Coverage:IRA and Keogh plans
- Table Types:Savings accumulation and withdrawal schedules
- Approach:Static lookup reference
- Target Stage:IRA/Keogh account holders
- Experience Level:All levels, with caveats on data currency
Our verdict“A niche reference worth having only if you want print lookup tables or deal with legacy Keogh accounts — everyone else should choose a modern calculator-based book.”
Retirement Calculator: How Much Money Do I Need to Retire?
Retirement Calculator: How Much Money Do I Need to Retire? earns its spot as the quick-answer option in this lineup. While most entries here, like The Retirement Dilemma, bury the math inside broader strategy chapters, this one puts a single question front and center: your retirement number. That narrow focus is the point — a reader who wants a rough savings target without wading through investing philosophy gets an answer fast.
The tradeoff is thinness. Compared with Your Retirement Equation, which walks you from calculation to action plan, this title stops at the estimate and offers little guidance on how to close the gap it reveals. With no ratings and sparse documentation, buyers are gambling on depth they may not get.
Pros:- Delivers a personalized retirement savings estimate based on your own financial inputs
- Single-purpose focus means no filler — the whole book answers one core question
- Useful starting point for long-term savings goal-setting before deeper planning
- Faster to work through than multi-topic planning guides in this roundup
Cons:- Sparse details on features and methodology make it hard to judge rigor before buying
- No user reviews or ratings available to validate the calculations
- Provides no follow-through on how to actually reach the number it gives you
Best for: Pre-retirees who want a fast, focused estimate of their savings target without a long educational read
Not ideal for: Readers who already know their number and need withdrawal or investment strategy — this covers the ‘how much,’ not the ‘how’
- Format:Guide/calculator workbook
- Primary Focus:Estimating total retirement savings needed
- Approach:Input-based estimation
- Planning Stage:Early goal-setting
- Strategy Coverage:Minimal — calculation-focused
- User Ratings:None available
Our verdict“Pick this if you want a single-question shortcut to your retirement number; skip it if you need the action plan that follows.”
Your Retirement Equation: Calculate How Much You Need to Retire and How to Get It in Time
Your Retirement Equation stands out as the pick for readers who want the ‘what now?’ after the math. Where Retirement Calculator: How Much Money Do I Need to Retire? stops at the estimate, this title pairs its calculation methods with saving strategies, timing guidance, and realistic goal-setting — a fuller loop from question to plan. Compared with Calculate Your FIRE Amount, it aims at traditional-age retirees rather than early retirement chasers, which shapes its assumptions about timelines and Social Security.
The compromise is depth. There are no proprietary calculators like those packaged with The Retirement Dilemma, and advanced planners may find the investment sections too general to act on. It teaches the equation, not the portfolio.
Pros:- Covers both the calculation and the strategy for reaching the target on time
- Practical calculation methods readers can apply to their own numbers
- Helps set realistic, time-anchored retirement goals rather than vague targets
- More actionable overall than estimate-only titles in this roundup
Cons:- Lacks detailed investment advice — you’ll need another resource for portfolio construction
- No tools, software, or workbook calculators included
- May feel too basic for readers with established retirement plans
Best for: Working adults within 10-15 years of retirement who want a readable path from number-crunching to an actual savings plan
Not ideal for: Experienced DIY investors and advanced planners — the investment advice stays at survey level
- Format:Strategy and calculation guide
- Primary Focus:Retirement number plus savings and timing plan
- Approach:Calculation methods with practical advice
- Planning Stage:Mid-career to pre-retirement
- Tools Included:None — methods only
- Target Audience:Traditional-age retirees
- Difficulty Level:Beginner to intermediate
Our verdict“This is the right choice if you want calculation and follow-through strategy in one place; advanced investors should look elsewhere for depth.”
How We Picked
I evaluated each calculator on four factors that actually affect buying decisions in this category. First, math transparency: does the tool show its assumptions (inflation, withdrawal rate, return rates) or hide them behind a single output number? Second, breadth of scenarios: a calculator that only answers “how much do I need” is worth less than one that also handles withdrawal strategy, taxes, and timing decisions. Third, usability: some of these are structured as step-by-step worksheets, others as reference tables, and that difference determines who can actually use them. Fourth, value relative to free alternatives — if a free online calculator does the same thing, a paid product needs to justify its existence with depth, context, or planning frameworks.
The ranking reflects a simple philosophy: calculators that change how you make decisions beat calculators that only produce numbers. That’s why dilemma-focused and strategy-driven options sit at the top, while single-purpose number-crunchers land lower — not because they’re bad at math, but because they leave the harder questions unanswered.
| retirement investment calculator | Format | Target Stage | Experience Level |
|---|---|---|---|
| The Retirement Dilemma: The 8 | Book (digital/print edition) | Pre-retirement and early retirement | Intermediate |
| How Much Is Enough: Calculatin | Book (digital/print edition) | Early accumulation phase | Beginner |
| Calculate Your FIRE Amount: Th | Book (digital/print edition) | Full accumulation journey | Beginner to intermediate |
| Retirement Investment Planning | Book (digital/print edition) | At or near retirement | Intermediate |
| The Retirement Account Calcula | Printed book with reference tables | IRA/Keogh account holders | All levels, with caveats on data currency |
| Retirement Calculator: How Muc | Guide/calculator workbook | — | — |
| Your Retirement Equation: Calc | Strategy and calculation guide | — | — |
Factors to Consider When Choosing Retirement Investment Calculators
Before choosing a retirement calculator, it helps to understand what separates a useful one from an expensive worksheet. These are the factors that shaped my rankings and the mistakes I see buyers make most often.
Know What Question You’re Actually Asking
The biggest mistake buyers make is purchasing a calculator before defining their question. “How much do I need to save?” is a completely different problem than “when can I afford to retire?” or “how should I withdraw my money in retirement?” A product built for accumulation is nearly useless for decumulation, and vice versa. If you’re 30 years from retirement, you need growth and savings-rate modeling. If you’re within five years, you need withdrawal sequencing, Social Security timing, and tax-bracket management. Buyers who skip this step often end up with two or three products when one well-chosen guide would have done the job. Write down your single most pressing question first, then match the product to it.
Assumptions Matter More Than Math
Every retirement calculator runs on assumptions — inflation rates, market returns, lifespan, withdrawal rates — and these inputs swing the output more than any formula does. A calculator assuming 7% returns versus 5% can produce targets hundreds of thousands of dollars apart. The problem is that many products bury or hard-code these assumptions, so you get a confident number built on guesses you never approved. Look for products that surface their assumptions clearly and let you adjust them. A slightly clunkier tool with visible inputs is safer than a sleek one with a black box. This single factor separated the top-rated picks from the middle of the pack in my comparison.
Free Tools First, Paid Depth Second
Honest truth: a basic savings-target number is free from dozens of online calculators, including those from brokerages and nonprofit retirement planners. Paying for a product only makes sense when it offers something free tools don’t — proprietary scenario modeling, dilemmas frameworks, withdrawal tables, or accountability through structured worksheets. Before buying anything in this category, spend an hour with two or three free calculators and note where they fall short. If a free tool answers your question fully, save your money. If you find yourself hitting the same wall repeatedly — taxes, timing, healthcare, sequence risk — that’s exactly when paid depth earns its price. The best products in this roundup are the ones that pick up where free calculators stop.
Format Determines Whether You’ll Actually Use It
A calculator you abandon after one session is worthless regardless of its quality. Some of these products are workbooks designed for a weekend of focused effort; others are reference tables you’ll consult repeatedly over years; others are narrative guides with embedded calculations. Match the format to your habits. If you skim rather than study, a dense table-based product will sit untouched. If you dislike screen-based planning, a printable workbook format beats an interactive tool you’ll never reopen. Buyers consistently underestimate this factor and overestimate their own willingness to work through a 200-page planning system. Be honest about your attention span before you buy.
Watch for One-Number Thinking
Many calculators produce a single savings target, which feels satisfying but is genuinely misleading. Your retirement need isn’t one number — it’s a range that shifts with retirement age, healthcare costs, market conditions in your first decade of withdrawals, and whether you downsize or relocate. Products that frame retirement as a single figure create false confidence. The stronger picks in this category model tradeoffs: retire two years later and save this much less; claim Social Security at 67 instead of 62 and gain this much monthly income. If a product’s entire pitch is “find your number,” treat that as a warning sign rather than a selling point. Decision frameworks beat single outputs almost every time.
Frequently Asked Questions
Do I still need a paid retirement calculator when free online calculators exist?
For a basic savings target, no — free tools from major brokerages handle that well. Paid products earn their price when you need decision frameworks that free calculators skip: withdrawal sequencing, Social Security claiming strategy, tax-aware withdrawals, or modeling retirement dilemmas like timing and healthcare. The top pick in this roundup exists specifically because free tools produce a number without helping you navigate the tradeoffs around it. If a free calculator leaves you with more questions than answers, that’s the signal a paid guide is worth it. If it fully answers your question, pocket the money and invest it instead.
Which of these calculators is best if I’m starting to save late?
Your Retirement Equation is built for exactly this situation, framing everything around a fixed countdown rather than an open-ended horizon. It focuses on catch-up contributions, adjusted expectations, and accelerated savings paths rather than the 40-year compounding assumptions most calculators make. The FIRE-oriented guides, by contrast, assume long time horizons and become less useful if you’re within 15 years of retirement with modest savings. Late starters should also prioritize products that address Social Security timing carefully, since delaying claims becomes one of the few levers that meaningfully changes outcomes. A calculator optimized for 25-year-olds can actively mislead someone starting at 50.
Are the FIRE calculators useful for traditional retirement planning?
Partially, but the framing matters more than buyers expect. FIRE calculators assume aggressive savings rates, decades-long withdrawal horizons, and often leaner spending — assumptions that fit traditional retirement poorly. If you plan to retire at 65 with a conventional lifestyle, the 4% rule discussions and savings-rate math in FIRE guides still apply, but the lifestyle assumptions will skew your target number. The reverse is also true: traditional calculators rarely handle 40-year retirements safely. Choose based on your actual timeline, not on which book has better reviews. The two FIRE picks in this roundup overlap heavily, so pick one, not both.
How accurate are retirement calculators, really?
They’re only as accurate as their assumptions, which is why transparency matters more than formula elegance. Most calculators project returns, inflation, and lifespan — three things nobody can predict — so treat every output as a scenario, not a forecast. The honest products acknowledge this by showing ranges and letting you stress-test with conservative inputs. A calculator that gives you one confident number without showing its assumptions is giving you false precision. Run your numbers through at least two different products with pessimistic, moderate, and optimistic assumptions; if the results roughly agree, you have a usable planning range. If they diverge wildly, the disagreement itself is valuable information about your plan’s fragility.
Should I buy multiple calculators or just one?
One, almost always. These products overlap far more than their marketing suggests, and working through two full planning systems usually produces confusion rather than clarity — different assumptions yield different targets, and you’ll have no way to reconcile them. The exception is pairing a broad decision-framework product with a narrow reference tool, like a savings guide plus the IRA and Keogh tables in The Retirement Account Calculator, since those serve genuinely different purposes. But buying three books that all calculate your retirement number guarantees nothing except three slightly different numbers. Pick the one that matches your situation, commit to its worksheets, and revisit in a year or when your circumstances change.
Conclusion
The right pick depends entirely on where you stand. Best overall goes to The Retirement Dilemma, which pairs 15 calculators with the decision frameworks that free tools never touch — the strongest value for serious planners. Best for beginners is Retirement Calculator: How Much Money Do I Need to Retire?, a low-commitment starting point that won’t overwhelm first-timers. Best for late starters is Your Retirement Equation, built around a countdown mentality rather than decades of compounding. Best for FIRE seekers is Calculate Your FIRE Amount for its step-by-step system, with How Much Is Enough as the philosophy-first alternative. Best for account-specific planning is The Retirement Account Calculator, whose IRA and Keogh tables are unmatched despite the dated format. Whichever you choose, pick one, work it through completely, and revisit your numbers annually — the calculator only helps if you actually run it.
Fall yard work Picks
leaf blowers
As an affiliate, we earn on qualifying purchases.