High-yield savings accounts can pay 10 to 20 times more interest than a standard big-bank savings account, yet most savers still park cash where they earn almost nothing. After comparing the leading options for 2026, The High-Yield Cash Guide (2026 Edition) stands out as the best overall pick because it covers both savings accounts and CDs with current, practical selection criteria rather than generic advice. Two other strong options: Getting Started with High-Yield Savings Accounts for nervous first-timers, and Dividend Growth Investing vs. High-Yield Savings Accounts for anyone deciding where a 4%-plus yield should actually live. The main tradeoff in this category is depth versus accessibility — some guides go deep on rate mechanics and strategy but overwhelm beginners, while simpler guides leave advanced savers wanting more. Keep reading for the full breakdown of which option fits your money style.

Get smart everyday buys delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
Key Takeaways
- Guides published or updated for 2026 clearly outperformed older titles, because rate environments, FDIC limits, and bank offerings shift fast enough to make pre-2024 advice misleading.
- The strongest picks explain WHERE to find top rates and HOW to evaluate safety, liquidity, and fees — books that only listed specific banks aged poorly.
- Beginner-focused titles like Getting Started with High-Yield Savings Accounts deliberately trade depth for reassurance, which makes them great entry points but poor long-term references.
- Comparison-driven guides (high-yield vs. standard savings, vs. CDs, vs. dividend investing) delivered more decision value than single-topic account guides.
- Several short titles padded thin content with motivational filler; page count correlated weakly with usefulness, so I weighted substance over length.





| high yield savings account | Format | Series | ASIN |
|---|---|---|---|
| What Your Bank Doesn’t Tell Yo | Kindle/Book | The Long-Term Wealth Series, Book 5 | B0HCWWTLLB |
| The High-Yield Cash Guide | Book | — | B0GPBXWTL6 |
| High-Yield Cash: The 5% Intere | Book | — | B0H6ZG2DPV |
| The Elite Savers of America: H | Book | Financial Freedom Series | B0F94BTCPL |
| My High-Yield Savings Account: | Book | Great Investing Book (Book 106) | B0BSV4B3YN |
| From Ordinary to Extraordinary | Book | — | — |
| Getting Started with High-Yiel | Book | Diverse Entrepreneurs (Book 130) | — |
| High-Yield Savings | Kindle / Book | Money Guide Series (Book 69) | — |
| Dividend Growth Investing vs. | Book | Superb Investing (Book 25) | — |
| My Three Favorite High-Yield S | Kindle Edition | Great Investing (Book 285) | — |
| High-Yield Savings Accounts vs | Kindle / Digital Book | Massive Passive Income Books | B0F1TYHNDD |
More Details on Our Top Picks
What Your Bank Doesn’t Tell You: How to Use High-Yield Savings Accounts, Roth IRAs, 401(k)s, HSAs, and Other Smart Accounts to Build Long-Term Wealth
This pick stands out as the widest-ranging title in the lineup, treating high-yield savings as one piece of a larger wealth machine alongside Roth IRAs, 401(k)s, and HSAs. Where The High-Yield Cash Guide (2026 Edition) drills into account selection, this book asks a different question: how all these accounts work together over decades. That framing makes it the strongest choice for readers who already have cash sitting in a standard savings account and want a full financial map, not just a better interest rate.
The tradeoff is focus. If your only goal is picking a savings account this week, much of the retirement and tax content will feel like a detour, and the account-by-account detail is thinner than in a dedicated guide.
Pros:- Covers high-yield savings alongside Roth IRAs, 401(k)s, and HSAs in one framework
- Frames cash accounts as part of a decades-long wealth strategy rather than an isolated product
- Part of an established series, so the approach carries some editorial continuity
- Reveals account mechanics banks rarely explain to customers
Cons:- Breadth comes at the cost of depth on any single account type
- No detailed description available, so the quality and rigor are hard to gauge before buying
Best for: Savers ready to coordinate emergency cash with retirement and tax-advantaged accounts as part of a long-term plan
Not ideal for: Readers who only want help choosing one high-yield account today — the breadth here dilutes that single decision
- Format:Kindle/Book
- Series:The Long-Term Wealth Series, Book 5
- Topics Covered:High-yield savings, Roth IRAs, 401(k)s, HSAs
- Focus:Long-term wealth building across multiple account types
- Angle:Strategies banks typically don’t share
- ASIN:B0HCWWTLLB
Our verdict“Choose this if you want savings strategy woven into a full wealth plan, and skip it if you only need account-picking advice.”
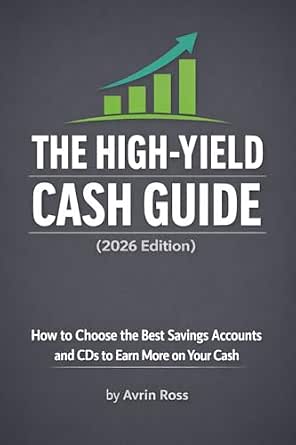
The High-Yield Cash Guide (2026 Edition): How to Choose the Best Savings Accounts and CDs to Earn More on Your Cash
Among these titles, this is the one that most directly answers the question a buyer actually has: which account should I put my cash in? By covering both high-yield savings accounts and CDs, it addresses a decision the other books largely ignore — whether to lock up money for a fixed rate or keep it liquid. Compared with What Your Bank Doesn’t Tell You, it trades big-picture retirement planning for hands-on selection criteria, and that narrowness is a strength if your money decisions are all cash-based.
The dated edition cuts both ways. A 2026 Edition label signals current rate context, but specific rates and bank names in any printed guide age quickly, so treat it as a framework rather than a rate table. Available source content is also thin, making depth hard to verify.
Pros:- Directly addresses account and CD selection, the decision most savers face
- Covers both liquid savings and fixed-term CDs in one comparison
- Recent edition suggests updated rate context and bank landscape
- Focused scope keeps the material actionable rather than sprawling
Cons:- Rate-specific guidance becomes stale as the interest-rate environment shifts
- Limited descriptive content available to gauge the book’s depth
Best for: First-time high-yield savers who want practical criteria for comparing savings accounts and CD terms
Not ideal for: Readers planning beyond cash — there’s no retirement or investing guidance here
- Format:Book
- Edition:2026 Edition
- Topics Covered:High-yield savings accounts and CDs
- Focus:Earning more on cash holdings
- Category:Personal Finance — Savings Accounts and CDs
- ASIN:B0GPBXWTL6
Our verdict“This makes the most sense for savers who want a practical choosing framework for cash accounts and CDs rather than a wealth philosophy.”
High-Yield Cash: The 5% Interest Strategy
The title alone tells you what this book is about: chasing a specific yield target rather than exploring accounts broadly. That single-mindedness sets it apart from The High-Yield Cash Guide (2026 Edition), which walks through general selection criteria — here the promise is a strategy built around a headline rate. For savers motivated by a concrete number, that framing can be more compelling than abstract advice, and it pairs well with the goal-driven approach of The Elite Savers of America.
The obvious risk is relevance. Rates near that level existed in a particular rate environment, and a strategy pinned to one number may not translate when yields move. With no description or review content available, buyers are going in with the least information of any title in this roundup — verification is essentially impossible before purchase.
Pros:- Built around a clear, motivating interest-rate target
- Short and focused on cash strategy rather than general finance
- Complements goal-based savings titles in this lineup
Cons:- A strategy tied to a specific rate loses relevance when the rate environment changes
- No product description or review content available to evaluate the author’s approach
Best for: Yield-chasers who want a strategy framed around a concrete interest-rate target
Not ideal for: Cautious buyers who need detailed descriptions and verifiable credentials before spending money on a finance book
- Format:Book
- Topic:High-yield cash strategy
- Core Concept:5% interest strategy
- Category:Personal Finance — Savings
- ASIN:B0H6ZG2DPV
Our verdict“Only worth a look if you’re comfortable buying on title promise alone and want a rate-targeted cash strategy.”
The Elite Savers of America: How to Save $10,000 in a High-Yield Savings Account (Financial Freedom Series, Book 175)
Rather than debating which bank offers the best rate, this book anchors everything to a concrete milestone: saving $10,000. That makes it the motivational counterpart to The High-Yield Cash Guide (2026 Edition) — where that title explains how to choose an account, this one focuses on the behavior and habits needed to actually fill it. For readers who have stalled out on saving and respond better to a target than to theory, that structure can work where broader guides don’t.
The flip side is a very specific dollar figure. Someone with $50,000 in cash already, or someone saving toward a different number, may find the framing too narrow. And at Book 175 in the Financial Freedom Series, the volume carries the feel of a mass-produced series entry rather than a deeply developed standalone guide.
Pros:- Built around a concrete, motivating savings goal rather than abstract principles
- Pairs goal-setting with high-yield account strategy so saved money earns more
- Part of a long-running series with a consistent financial-freedom philosophy
Cons:- The $10,000 target may not map to your actual savings needs
- Deep into a numbered series, which can indicate formulaic rather than in-depth content
- No detailed description available to confirm the level of substance
Best for: Beginner savers who need a defined $10,000 target and habit-building structure more than technical account analysis
Not ideal for: Experienced savers or those with different goals — the fixed milestone framing will feel limiting
- Format:Book
- Series:Financial Freedom Series
- Book Number:175
- Core Goal:Saving $10,000 in a high-yield savings account
- Focus:Savings habits and financial freedom
- ASIN:B0F94BTCPL
Our verdict“This pick makes the most sense for a first-time saver who wants a clear finish line; skip it if you already have a funded plan.”
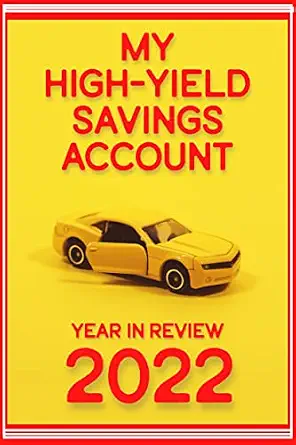
My High-Yield Savings Account: Year in Review 2022 (Great Investing Book 106)
Every other title in this roundup is instructional; this one is a documented account of actual results over a full year. That case-study format has genuine value — instead of hypothetical projections, you see what a real high-yield savings account did month to month through 2022, a year when rates were rising fast. Readers who distrust glossy promises may find a transparent ledger more persuasive than advice books like High-Yield Cash: The 5% Interest Strategy.
But the limitations are hard to overlook. A year-specific snapshot from a unique rate-hike cycle won’t repeat, so the instructive value fades with each passing year. It also documents one person’s experience rather than a repeatable method, and the niche appeal means it works best as a supplement beside a broader guide — not as your only book on the subject.
Pros:- Real-world documented performance rather than hypothetical examples
- Covers a full year, showing month-to-month rate and balance changes
- Transparent case-study format builds trust that advice books can’t
- Part of the Great Investing Book series alongside other account-specific titles
Cons:- Tied to 2022’s unusual rising-rate environment, so conclusions may not transfer
- Very niche: one person’s account history with limited general applicability
Best for: Curious savers who want to see real, documented account performance as a companion to a strategy guide
Not ideal for: Anyone seeking a current, repeatable savings playbook — a 2022 case study is dated and singular by nature
- Format:Book
- Series:Great Investing Book (Book 106)
- Content Type:Year-in-review case study
- Period Covered:Calendar year 2022
- Focus:Real-world high-yield savings account performance
- ASIN:B0BSV4B3YN
Our verdict“Worth adding if you want evidence of how a high-yield account actually performed, but pair it with a current guide rather than relying on it alone.”
From Ordinary to Extraordinary Savings: Harnessing the Power of High-Yield Accounts
Figuring out where this book fits is genuinely difficult because the listing provides no description, no content details, and no reader feedback to evaluate. Compared with titles like Getting Started with High-Yield Savings Accounts, which at least signals its audience and approach through its series branding, this one offers nothing to anchor a buying decision. The title suggests an inspirational, motivational angle — moving from ‘ordinary’ rates to ‘extraordinary’ growth — which may appeal to readers who want encouragement alongside education. But that framing could also mean more rhetoric than practical instruction. Anyone shopping this roundup should treat this as a blind purchase unless they find a preview or sample elsewhere. The High-Yield Cash Guide (2026 Edition) makes a stronger case for readers who want concrete account-selection guidance with transparent scope.
Pros:- Motivational framing may resonate with savers who respond to encouragement over dry instruction
- Broad topic allows room to cover mindset alongside mechanics
- Potentially useful as a confidence-building companion to more technical guides
Cons:- No product description or content information available anywhere to verify what the book actually teaches
- Impossible to confirm depth, accuracy, or structure before purchase
- Higher duplicate-content risk given the crowded self-published finance space
Best for: Motivation-driven readers willing to gamble on an unvetted title with an inspirational savings angle
Not ideal for: Anyone who needs to know exactly what a book covers before buying — the total absence of content detail makes this a risky purchase
- Format:Book
- Topic:High-yield savings accounts and savings growth strategies
- Genre:Personal Finance
- Content Verification:No description or specifications provided
- Target Audience:Unspecified
- Depth:Unknown
Our verdict“Only worth considering if you can preview it first, since the complete lack of listing information makes this the least verifiable pick in the roundup.”
Getting Started with High-Yield Savings Accounts: Overcoming Your Banking Fears (Diverse Entrepreneurs Book 130)
Most high-yield savings guides assume you are already comfortable with banking; this one is built for readers who are not. The focus on overcoming banking anxieties sets it apart from everything else in this lineup, including the more mechanically thorough High-Yield Savings, CDs, and Money Market Accounts: The Complete Beginner’s Guide, which teaches the products but not the confidence to use them. Its placement in the Diverse Entrepreneurs series also means the framing speaks to readers historically underserved by mainstream finance media — a genuine differentiator, not a marketing footnote. The tradeoff is scope: this is a getting started book, so readers who already have an emergency fund and simply want to compare rates across banks will outgrow it quickly. Pair it with a selection guide rather than expecting it to be your only resource.
Pros:- Directly addresses banking anxiety, a barrier most finance books ignore entirely
- Speaks specifically to diverse entrepreneurs rather than a generic audience
- Practical step-by-step approach builds momentum for total beginners
- Part of a structured series readers can continue with
Cons:- Content depth cannot be verified from available listing information
- Beginner-only scope makes it redundant for anyone past the first-account stage
Best for: First-generation savers and diverse entrepreneurs who feel intimidated by banks and need confidence-building before tactics
Not ideal for: Experienced savers comparing current rates — this addresses emotional barriers, not account-by-account optimization
- Series:Diverse Entrepreneurs (Book 130)
- Format:Book
- Topic:High-yield savings accounts for beginners
- Special Focus:Overcoming banking fears and building confidence
- Target Audience:Diverse entrepreneurs and banking beginners
- Depth:Beginner / getting-started level
Our verdict“The right starting point if fear of banking — not lack of rate knowledge — is what is keeping you from opening a high-yield account.”
High-Yield Savings, CDs, and Money Market Accounts: The Complete Beginner’s Guide (Money Guide Series Book 69)
Where most books here cover one savings vehicle, this guide covers three: high-yield savings, CDs, and money market accounts — which matches how real savers actually split cash between liquidity and yield. That breadth is its core advantage over narrower titles like My Three Favorite High-Yield Savings Accounts, which stays inside a single category. A reader finishing this book should understand not just what each vehicle does but when a CD ladder beats a savings account and why a money market fund might sit in between — exactly the decision framework beginners lack. The tradeoff for covering three products in one beginner volume is that none receives exhaustive treatment. Readers wanting a deep, edition-dated account-shopping resource will still want something like The High-Yield Cash Guide (2026 Edition) alongside it for current rates and account picks.
Pros:- Covers high-yield savings, CDs, and money market accounts in a single comparative framework
- Genuinely beginner-friendly with no prior knowledge required
- Part of an established Money Guide Series with consistent structure
- Teaches vehicle selection logic, which stays useful even as rates change
Cons:- Three topics in one beginner book means each gets limited depth
- No review content available to gauge writing quality or accuracy
Best for: Beginners deciding between cash savings vehicles who want one book to explain all three options side by side
Not ideal for: Readers who already know they want a high-yield savings account specifically and need account recommendations, not vehicle comparisons
- Series:Money Guide Series (Book 69)
- Format:Kindle / Book
- Topics Covered:High-yield savings, CDs, money market accounts
- Experience Level:Beginner — no prior knowledge required
- Genre:Personal Finance
- Scope:Multi-vehicle comparison guide
Our verdict“The strongest single starting point for beginners who want to understand the whole cash-savings landscape before committing money anywhere.”
Dividend Growth Investing vs. High-Yield Savings Accounts: How to Get a 4% Yield (Superb Investing Book 25)
This is the only title in the roundup that treats high-yield savings as one half of a comparison rather than the whole story, stacking it against dividend growth investing with a concrete 4% yield target. That framing makes it the natural follow-up to pure savings books like High-Yield Savings, CDs, and Money Market Accounts: The Complete Beginner’s Guide — once you understand the safe baseline, this book asks whether you should take on market risk to match or beat it. The specific yield number is a genuine strength: it converts an abstract debate into a benchmark you can measure portfolios against. The flip side is that the title’s promise ages unevenly — when savings rates sit near or above 4%, the comparison shifts, and when they fall, the investing side dominates. It also assumes more risk tolerance than a savings-focused reader may have, so cautious savers should approach it as a stretch pick.
Pros:- Directly compares two income strategies rather than covering either in isolation
- Concrete 4% yield target gives readers a measurable benchmark
- Bridges the gap between savings-account savers and beginning investors
- Part of the established Superb Investing series
Cons:- Narrow subject matter limits value for general personal-finance readers
- Rate-dependent framing becomes misleading as savings yields move above or below 4%
Best for: Savers ready to graduate from cash accounts and evaluate whether dividend stocks can beat their savings yield
Not ideal for: Risk-averse readers who want principal protection only — this book’s investing half involves market volatility savings accounts never carry
- Series:Superb Investing (Book 25)
- Format:Book
- Topic:Dividend growth investing vs. high-yield savings accounts
- Target Yield:4%
- Genre:Personal Finance / Investing
- Experience Level:Intermediate — assumes comfort with basic investing concepts
Our verdict“Worth reading once your emergency fund is set and you are deciding whether dividend stocks deserve a share of the money currently earning savings interest.”
My Three Favorite High-Yield Savings Accounts: Get Paid While You Save (Great Investing Book 285)
Of every book in this roundup, this one has the tightest scope: three specific accounts, explained by an author sharing personal picks. That is simultaneously its appeal and its limitation. Compared with the broader vehicle education in High-Yield Savings, CDs, and Money Market Accounts, this book skips theory and goes straight to named recommendations — useful if you want someone to just tell you where to park cash. Its sibling title, My High-Yield Savings Account: Year in Review 2022, shares the same first-person, account-specific DNA, so readers who liked that format will feel at home here. The unavoidable problem is time sensitivity: banks change rates and close accounts to new customers constantly, so any shortlist of three will age faster than a book teaching selection criteria. Treat it as a starting shortlist to verify against current rates, not a final answer.
Pros:- Delivers concrete named accounts instead of abstract selection advice
- Short focused read for savers who want answers, not theory
- First-person perspective adds authenticity to the picks
- Part of the extensive Great Investing book series
Cons:- Specific account picks and referenced rates can become outdated quickly
- Extremely limited scope offers little transferable knowledge about evaluating accounts yourself
Best for: Decision-fatigued savers who want a short named shortlist to research rather than a framework for evaluating every bank themselves
Not ideal for: Readers who want durable, rate-agnostic guidance — a three-account list loses relevance as soon as yields or account availability change
- Series:Great Investing (Book 285)
- Format:Kindle Edition
- Genre:Personal Finance / Investing
- Topic:Three recommended high-yield savings accounts
- Approach:First-person account recommendations
- Scope:Narrow — account shortlist only
- Shelf Life:Rate-sensitive; verify current rates before acting
Our verdict“A quick shortlist generator for savers who want three leads to research today, provided they verify every rate before acting on it.”
High-Yield Savings Accounts vs. Standard Savings Accounts: We Should All Love Yield (Massive Passive Income Books, Book 176)
This entry stands out as the only book in this lineup built entirely around a single question: is a high-yield account actually better than a standard one? Where The High-Yield Cash Guide (2026 Edition) spreads itself across savings accounts and CDs, and High-Yield Savings, CDs, and Money Market Accounts covers three account types at once, this volume keeps a narrow, comparative focus. That narrowness is its strength and its weakness. Readers who want a clear side-by-side framing of yield differences will find the premise useful, but anyone hoping for broader coverage— Roth IRAs, 401(k)s, HSAs— will be better served by What Your Bank Doesn’t Tell You. Compared with The Elite Savers of America, which targets a concrete $10,000 goal, this book is more conceptual than actionable. Sparse detail and its place deep in a long series make it a situational pick rather than a first choice.
Pros:- Part of an established series on passive income, so the framing fits a larger learning path
- Tightly focused on the high-yield versus standard comparison, which most competitors gloss over
- Short, single-topic format suits readers who want a quick conceptual primer
- Directly relevant to anyone deciding whether to switch banks
Cons:- Very niche subject matter with limited scope compared with multi-account guides in this roundup
- Little available detail to verify depth, examples, or writing quality before buying
- Book 176 in a long series may assume familiarity with earlier concepts
Best for: Readers who specifically want a focused explanation of why high-yield beats standard savings, especially those already following the Massive Passive Income series
Not ideal for: Beginners wanting broad, hands-on guidance across multiple account types, since the scope here is limited to a single comparison and lacks verifiable depth
- ASIN:B0F1TYHNDD
- Format:Kindle / Digital Book
- Series:Massive Passive Income Books
- Book Number:176
- Genre:Personal Finance / Savings
- Core Topic:High-yield vs. standard savings accounts
Our verdict“Pick this only if you want a short, comparison-driven primer on yield differences and already trust the Massive Passive Income series; otherwise the broader guides here offer more complete instruction.”
How We Picked
I evaluated each guide against what actually determines whether a reader ends up with a better savings outcome: accuracy and currency of the rate and regulatory information, actionability (does the reader finish knowing exactly which account features to look for), credibility of the framework (FDIC insurance, liquidity, fee traps, withdrawal rules), and audience fit — a beginner and a six-figure saver need very different books. Guides that explained how to compare accounts across banks consistently outranked ones that simply named banks, because institutions change but selection logic endures.
The ranking also reflects scope versus depth tradeoffs. Comprehensive guides covering savings, CDs, and money markets ranked higher for most readers because they help you place cash across the full yield spectrum. Niche titles earned spots only when their narrow focus delivered genuinely better insight than the generalists — for example, the dividend-versus-savings comparison is the only pick that seriously addresses the question of when yield belongs in the market instead of the bank.
| high yield savings account | Format | ASIN |
|---|---|---|
| What Your Bank Doesn’t Tell Yo | Kindle/Book | B0HCWWTLLB |
| The High-Yield Cash Guide | Book | B0GPBXWTL6 |
| High-Yield Cash: The 5% Intere | Book | B0H6ZG2DPV |
| The Elite Savers of America: H | Book | B0F94BTCPL |
| My High-Yield Savings Account: | Book | B0BSV4B3YN |
| From Ordinary to Extraordinary | Book | — |
| Getting Started with High-Yiel | Book | — |
| High-Yield Savings | Kindle / Book | — |
| Dividend Growth Investing vs. | Book | — |
| My Three Favorite High-Yield S | Kindle Edition | — |
| High-Yield Savings Accounts vs | Kindle / Digital Book | B0F1TYHNDD |
Factors to Consider When Choosing High Yield Savings Accounts
Choosing where and how to pursue high-yield savings involves more than chasing the biggest advertised number. These are the factors that separate savers who genuinely benefit from those who get lured by headline rates and end up frustrated.Advertised Rate vs. What You Actually Earn
The most common mistake savers make is comparing headline APYs without reading the fine print. Many accounts offer a teaser rate that drops after an introductory period, or tiered rates where the advertised yield only applies to balances above a threshold you’ll never reach. Others cap the high rate on a small portion of your balance. Before committing, confirm whether the rate is ongoing or promotional, whether it applies to your full balance, and how the bank has historically adjusted rates when the Fed moves. A slightly lower rate from a stable institution often beats a flashy one that quietly drops six months in.
FDIC Insurance and Institution Type
Yield means nothing if the institution behind it fails. FDIC insurance covers $250,000 per depositor, per bank, per ownership category, and understanding that limit matters more as your cash grows. Many of the best rates come from online-only banks and credit unions rather than household names — that’s not inherently risky if they’re federally insured, but you should verify the insurance before depositing, not after. If your balance will exceed the limit, some fintech platforms spread deposits across multiple partner banks to extend coverage, though that structure adds a layer you should understand. Savers with large cash positions may need to split funds across institutions deliberately.
Access, Liquidity, and Transfer Speed
High-yield accounts are typically online-first, which means no branches and no same-day teller access. The practical question is how fast money moves: ACH transfers to your checking account can take one to three business days, which matters enormously in an emergency. Check whether the bank offers instant external transfers, an ATM card, or wire capability, and whether outgoing transfers are capped. A common setup is keeping one to two months of expenses in a local checking account while the rest earns yield elsewhere — a structure that costs you almost nothing in interest but eliminates the liquidity problem entirely.
Fees, Minimums, and Rate Traps
The best high-yield accounts charge no monthly maintenance fee and require no minimum balance, but not all do — and a $10 monthly fee can wipe out the entire yield advantage on a modest balance. Watch for accounts that waive fees only if you maintain direct deposits or a linked checking relationship, which quietly locks you into the bank’s ecosystem. Also be wary of savings accounts that limit you to six withdrawals per cycle; exceeding the cap can trigger fees or even account closure. Read the fee schedule end to end before opening, because the yield is marketed loudly and the fees are not.
High-Yield Savings vs. Alternatives
A high-yield savings account is one tool among several, and picking the wrong one for your goal is expensive. Money market accounts and CDs frequently beat savings rates if you can lock funds or maintain higher balances — a CD ladder can out-earn a savings account while sacrificing flexibility. Treasury bills and I bonds offer tax advantages that raise the effective yield for higher earners. Meanwhile, money you won’t touch for a decade usually belongs in investments, not cash, no matter how good the rate looks. The savviest cash strategy usually layers these vehicles rather than choosing one.
Knowing When to Switch
Rate leadership rotates constantly — the bank paying the best rate this year rarely holds the top spot two years running. Savers who switch accounts every time a competitor pays 0.2% more often find the effort and paperwork exceed the gain, especially below roughly $50,000 in savings. A better rule is to review your rate once or twice a year and switch only when the gap is meaningful and persistent, not promotional. Keep an eye on whether your bank is following the broader rate environment; a bank that lags every Fed cut but never leads any hike is signaling that it profits from inertia. Loyalty to a bank earns you nothing — the institution will not reward it.
Frequently Asked Questions
How much money do I need before a high-yield savings account is worth it?
Far less than most people assume. If an online account has no fees and no minimum — and the strongest options in this comparison emphasize that structure — even a few hundred dollars earns meaningfully more than it would at a traditional big bank paying near zero. The math scales with your balance: on $10,000, the gap between a 4% APY and a 0.1% APY is roughly $390 per year, which is real money for zero additional risk. The main threshold to think about isn’t a minimum deposit but the $250,000 FDIC insurance limit, which may require splitting funds across banks once your balance grows large. The short answer is that there is no practical floor — the sooner you move idle cash, the more compounding works in your favor.
Are online high-yield savings accounts safe compared to big banks?
Yes, provided the institution is federally insured — that’s the single check that matters. An online bank with FDIC insurance carries the same protection on deposits as a national brand: up to $250,000 per depositor, per bank, per ownership category, backed by the full faith of the US government. Online banks can pay more precisely because they lack branch networks and their overhead is lower, not because they take more risk with your money. The genuine risks are different ones: slower customer service when something goes wrong, transfer delays when you need funds urgently, and occasional confusion over whether a fintech app is itself a bank or just a front for partner banks. Verify insurance directly on the FDIC’s BankFind tool rather than trusting the app’s marketing page, and the safety question largely resolves itself.
Will the rate on my high-yield account stay the same?
No — high-yield savings rates are variable and follow the broader interest rate environment, moving when the Federal Reserve changes its benchmark rate. When the Fed cuts, your APY will usually fall within days or weeks; when it hikes, the best online banks raise rates quickly too, while big traditional banks drag their feet. This variability is exactly why the guides in this roundup that teach selection criteria rank higher than ones listing specific banks — the names change, but the method of evaluating rate stability and institution behavior stays useful. If you want certainty, that’s what CDs offer: a fixed rate for a fixed term, at the cost of access. Many savers split the difference by holding their emergency fund in savings and longer-horizon cash in a CD ladder.
Should I put my emergency fund in a high-yield account or a CD?
An emergency fund belongs in a high-yield savings account, not a CD, because the defining feature of emergency money is that you need it without warning. CDs charge early-withdrawal penalties that can eat several months of interest, and in a true emergency you don’t get to choose the timing. A high-yield savings account keeps every dollar accessible within a few business days while still earning a competitive rate. The hybrid approach works well once your fund exceeds six months of expenses: keep the first tranche fully liquid in savings, and ladder the surplus into CDs for a higher locked rate. The comparison guides in this roundup — particularly the ones covering CDs alongside savings accounts — walk through that split in more detail.
Do I need to close my current savings account to switch?
No, and you usually shouldn’t. The cleanest approach is to open the high-yield account first, link it to your existing checking account, move the funds once the link is verified, and only then decide what to do with the old savings account. Keeping your checking relationship intact preserves your bill-pay setup and direct deposits while the new account earns yield. If the old account charges fees or carries a balance requirement, close it once the transfer confirms — dormant accounts with small balances are a common way money gets forgotten. One caution: leave a small buffer in checking during the transition, because the first ACH transfer can take several days to clear and you don’t want a missed payment while funds are in transit.
Conclusion
The right pick here depends less on which guide is objectively best and more on where you are in your savings journey. For most readers, The High-Yield Cash Guide (2026 Edition) is the best overall choice — it covers savings accounts, CDs, and selection criteria with current information, so it stays useful after you’ve opened the account. For best value, High-Yield Savings Accounts vs. Standard Savings Accounts delivers the core argument and decision framework without demanding a big time investment.
Beginners should start with Getting Started with High-Yield Savings Accounts, which tackles banking anxiety directly, or The Complete Beginner’s Guide if they want money markets and CDs explained alongside savings. For a specific need — deciding whether yield belongs in the market — Dividend Growth Investing vs. High-Yield Savings Accounts is the only pick that takes that question seriously. And if your goal is a concrete savings milestone, The Elite Savers of America is built around reaching that first $10,000. Whatever you choose, the underlying lesson every strong guide agrees on: idle cash in a low-rate account is a silent, ongoing loss, and moving it is one of the lowest-effort financial wins available.
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.